Deductible and covered scope
The deductible is the owner’s portion under the applicable claim terms. Work outside the covered scope and upgrades can also affect the amount the owner pays.
Practical roofing answers for your Merriam property. A free roof inspection helps connect the information to the roof you have.
Free roof inspections. A roofer walks the roof when conditions allow.
Roofing work and an insurance claim answer different questions. The roof scope explains what needs repair or replacement. The policy and cause of loss determine what the insurer covers.
Damage findings, property history and event evidence help explain a storm concern. An inspection does not date every mark, and a nearby weather report does not prove damage at an address. Report a concern to the insurer promptly and follow the policy’s reporting requirements.
A covered roof claim can still leave costs with the owner. The actual policy and insurer’s determination control.
The deductible is the owner’s portion under the applicable claim terms. Work outside the covered scope and upgrades can also affect the amount the owner pays.
Replacement-cost and depreciated-value terms work differently. Some policies have conditions for recovering depreciation after work; others limit payment differently. Read the actual claim explanation with the insurer.
The construction scope needs to describe the failed parts and the work they require. Tear-off, decking, flashing and related assembly work can matter even when the visible damage looks small. Coverage for those items is a separate policy decision.
We help explain the roofing condition and the repair or replacement options. The insurer handles the coverage and claim determination. Keeping those roles clear makes it easier to understand which question is still unresolved.
Storm damage roofing service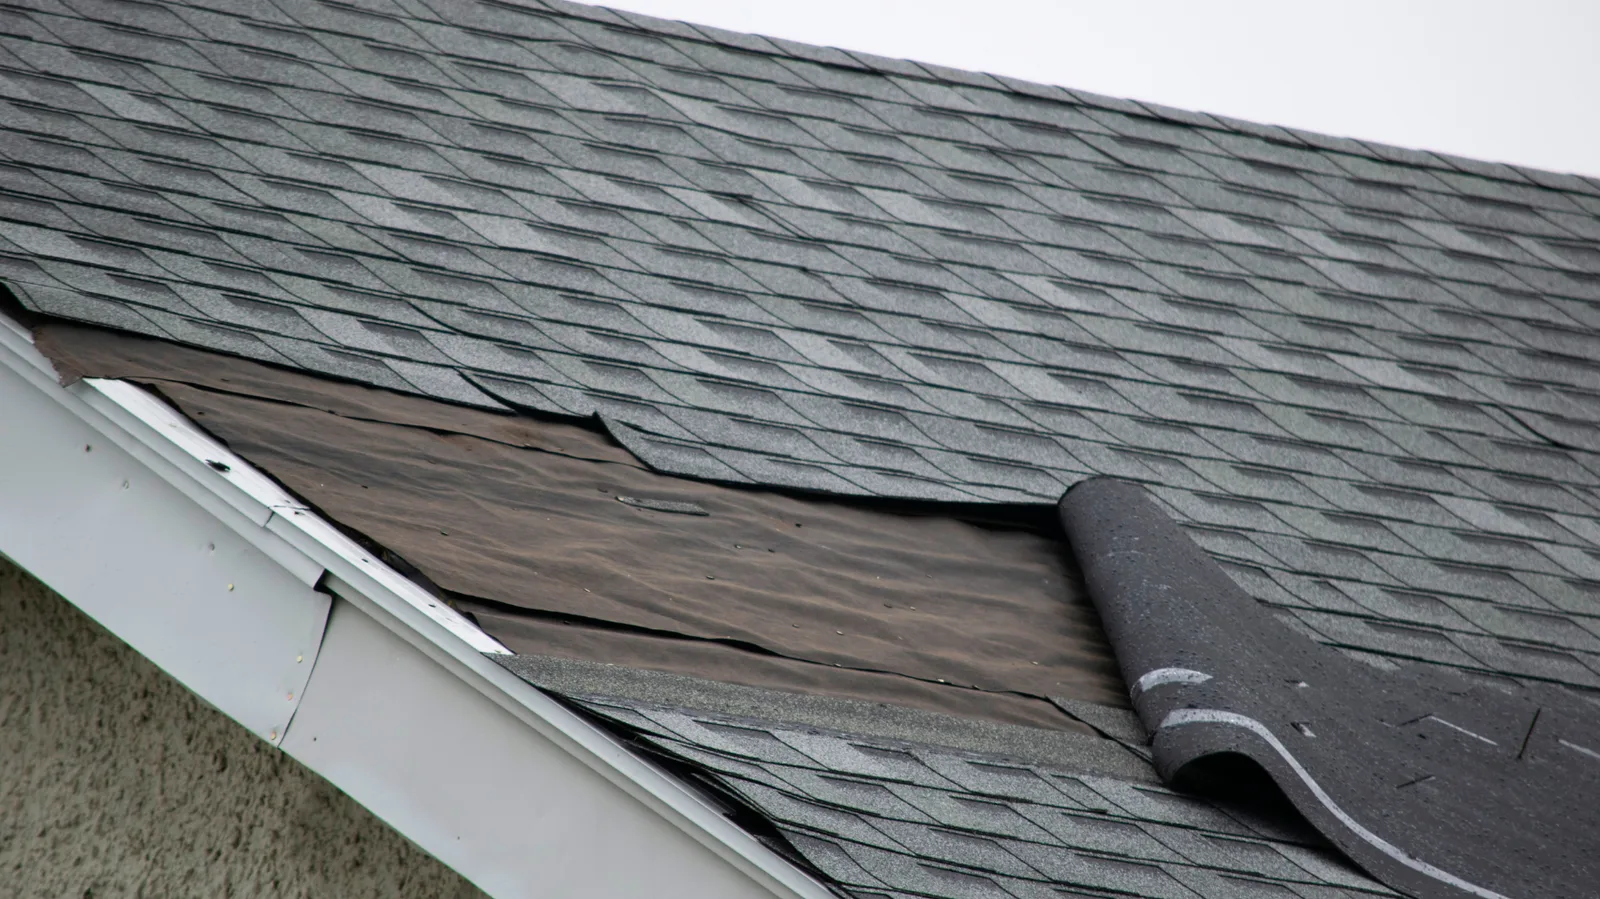
An old roof does not become covered simply because it needs replacement. The cause and policy terms matter.
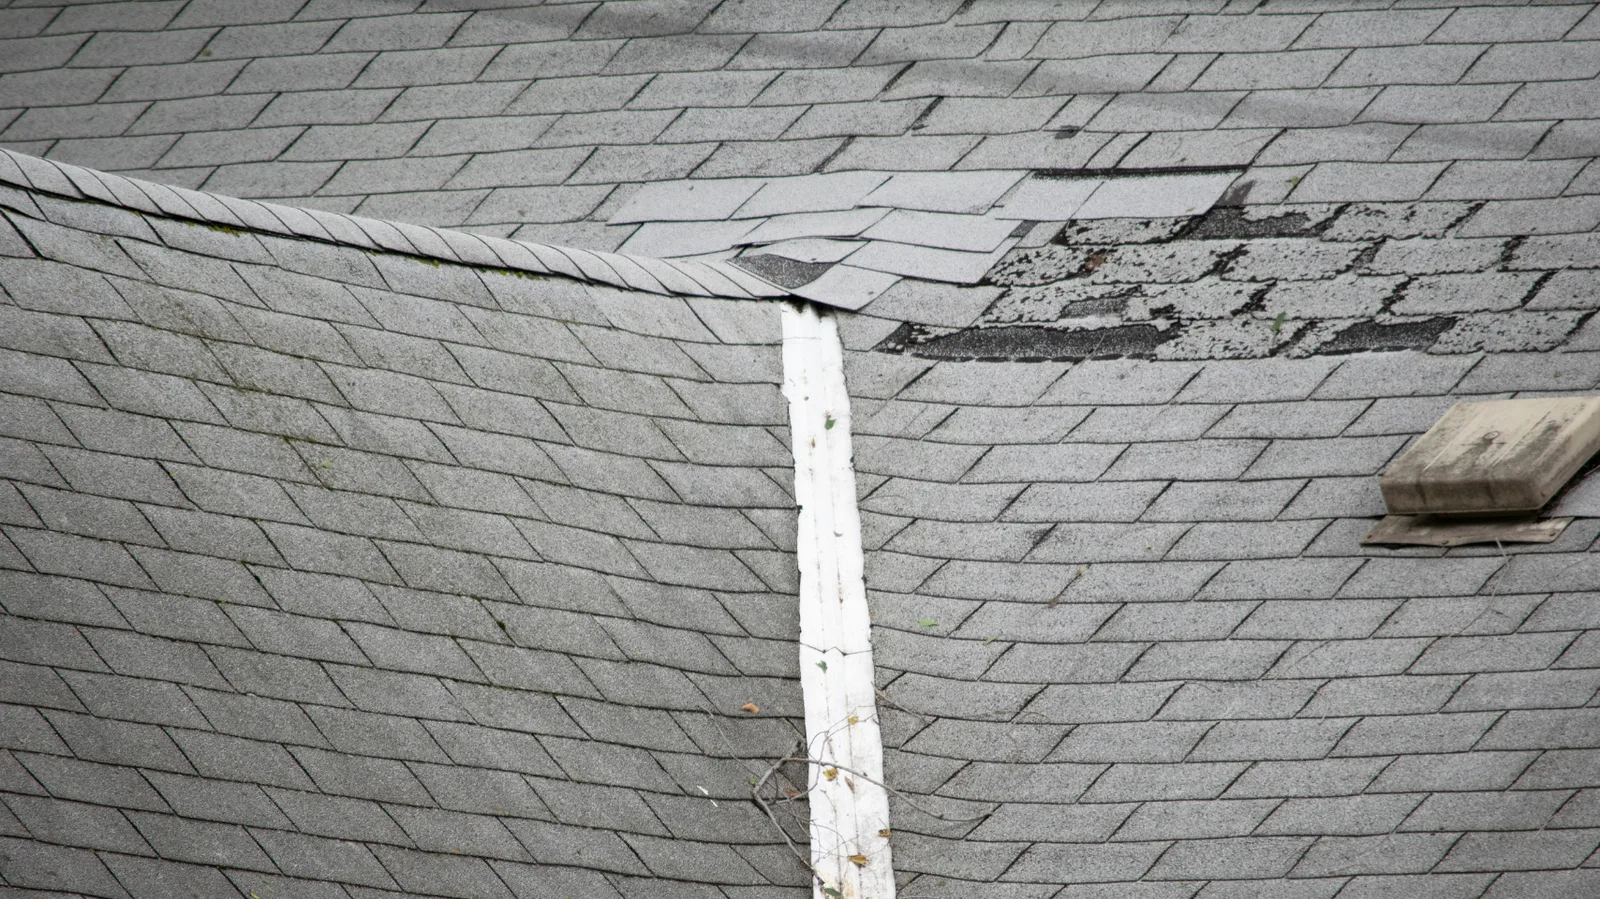
The covering and connections show what needs work. Prior repairs and when a change was noticed help establish context.
The cost guide explains a bounded replacement scenario. It does not predict an insurer’s allowance or the owner’s final claim balance.
Tell us what changed and when you noticed it. Request a free roof inspection to discuss the roof condition.
(913) 808-3279